You send your invoices as PDFs, built from a template you cobbled together yourself. A business client replies three weeks later saying it never arrived.
That conversation has an expiry date. Electronic invoicing is becoming mandatory for every business established in France, one-person companies included.
Your invoices to other businesses will travel through a state-approved platform, inside a file that software can read on its own. Two deadlines frame the switch. Being able to receive from September 1, 2026, then issuing from September 1, 2027 for small companies and sole traders.
You will leave this page knowing which obligations apply to you depending on who you bill, which date actually matters for you, and how to pick a tool without losing a weekend to it. No accounting background required.
A PDF sent by email is not an electronic invoice
Under the reform, an electronic invoice packs two things into one file. A document you and your client can read, and structured data a machine can process by itself.
That data is written in XML, a tagged text format that looks a lot like HTML. The tax authority reads the amount before tax, the VAT rate applied and the identity of both companies straight from it.
Three formats are accepted by the reform:
- Factur-X: a normal PDF with the XML file embedded inside it. The easiest one for a human to read.
- UBL: pure XML, widely used in cross-border trade.
- CII: pure XML as well, born from United Nations work on trade documents.
Your invoicing software builds that file for you. You keep typing your line items the way you always have.
Going paperless and issuing an electronic invoice are two different things. Scanning a paper document or exporting it to PDF removes the paper, but creates no structured data at all. The reform demands both layers.
E-invoicing and e-reporting, two obligations people mix up
The reform has two halves. Plenty of freelancers only hear about the first one and assume they are out of scope.
E-invoicing covers your business-to-business invoices
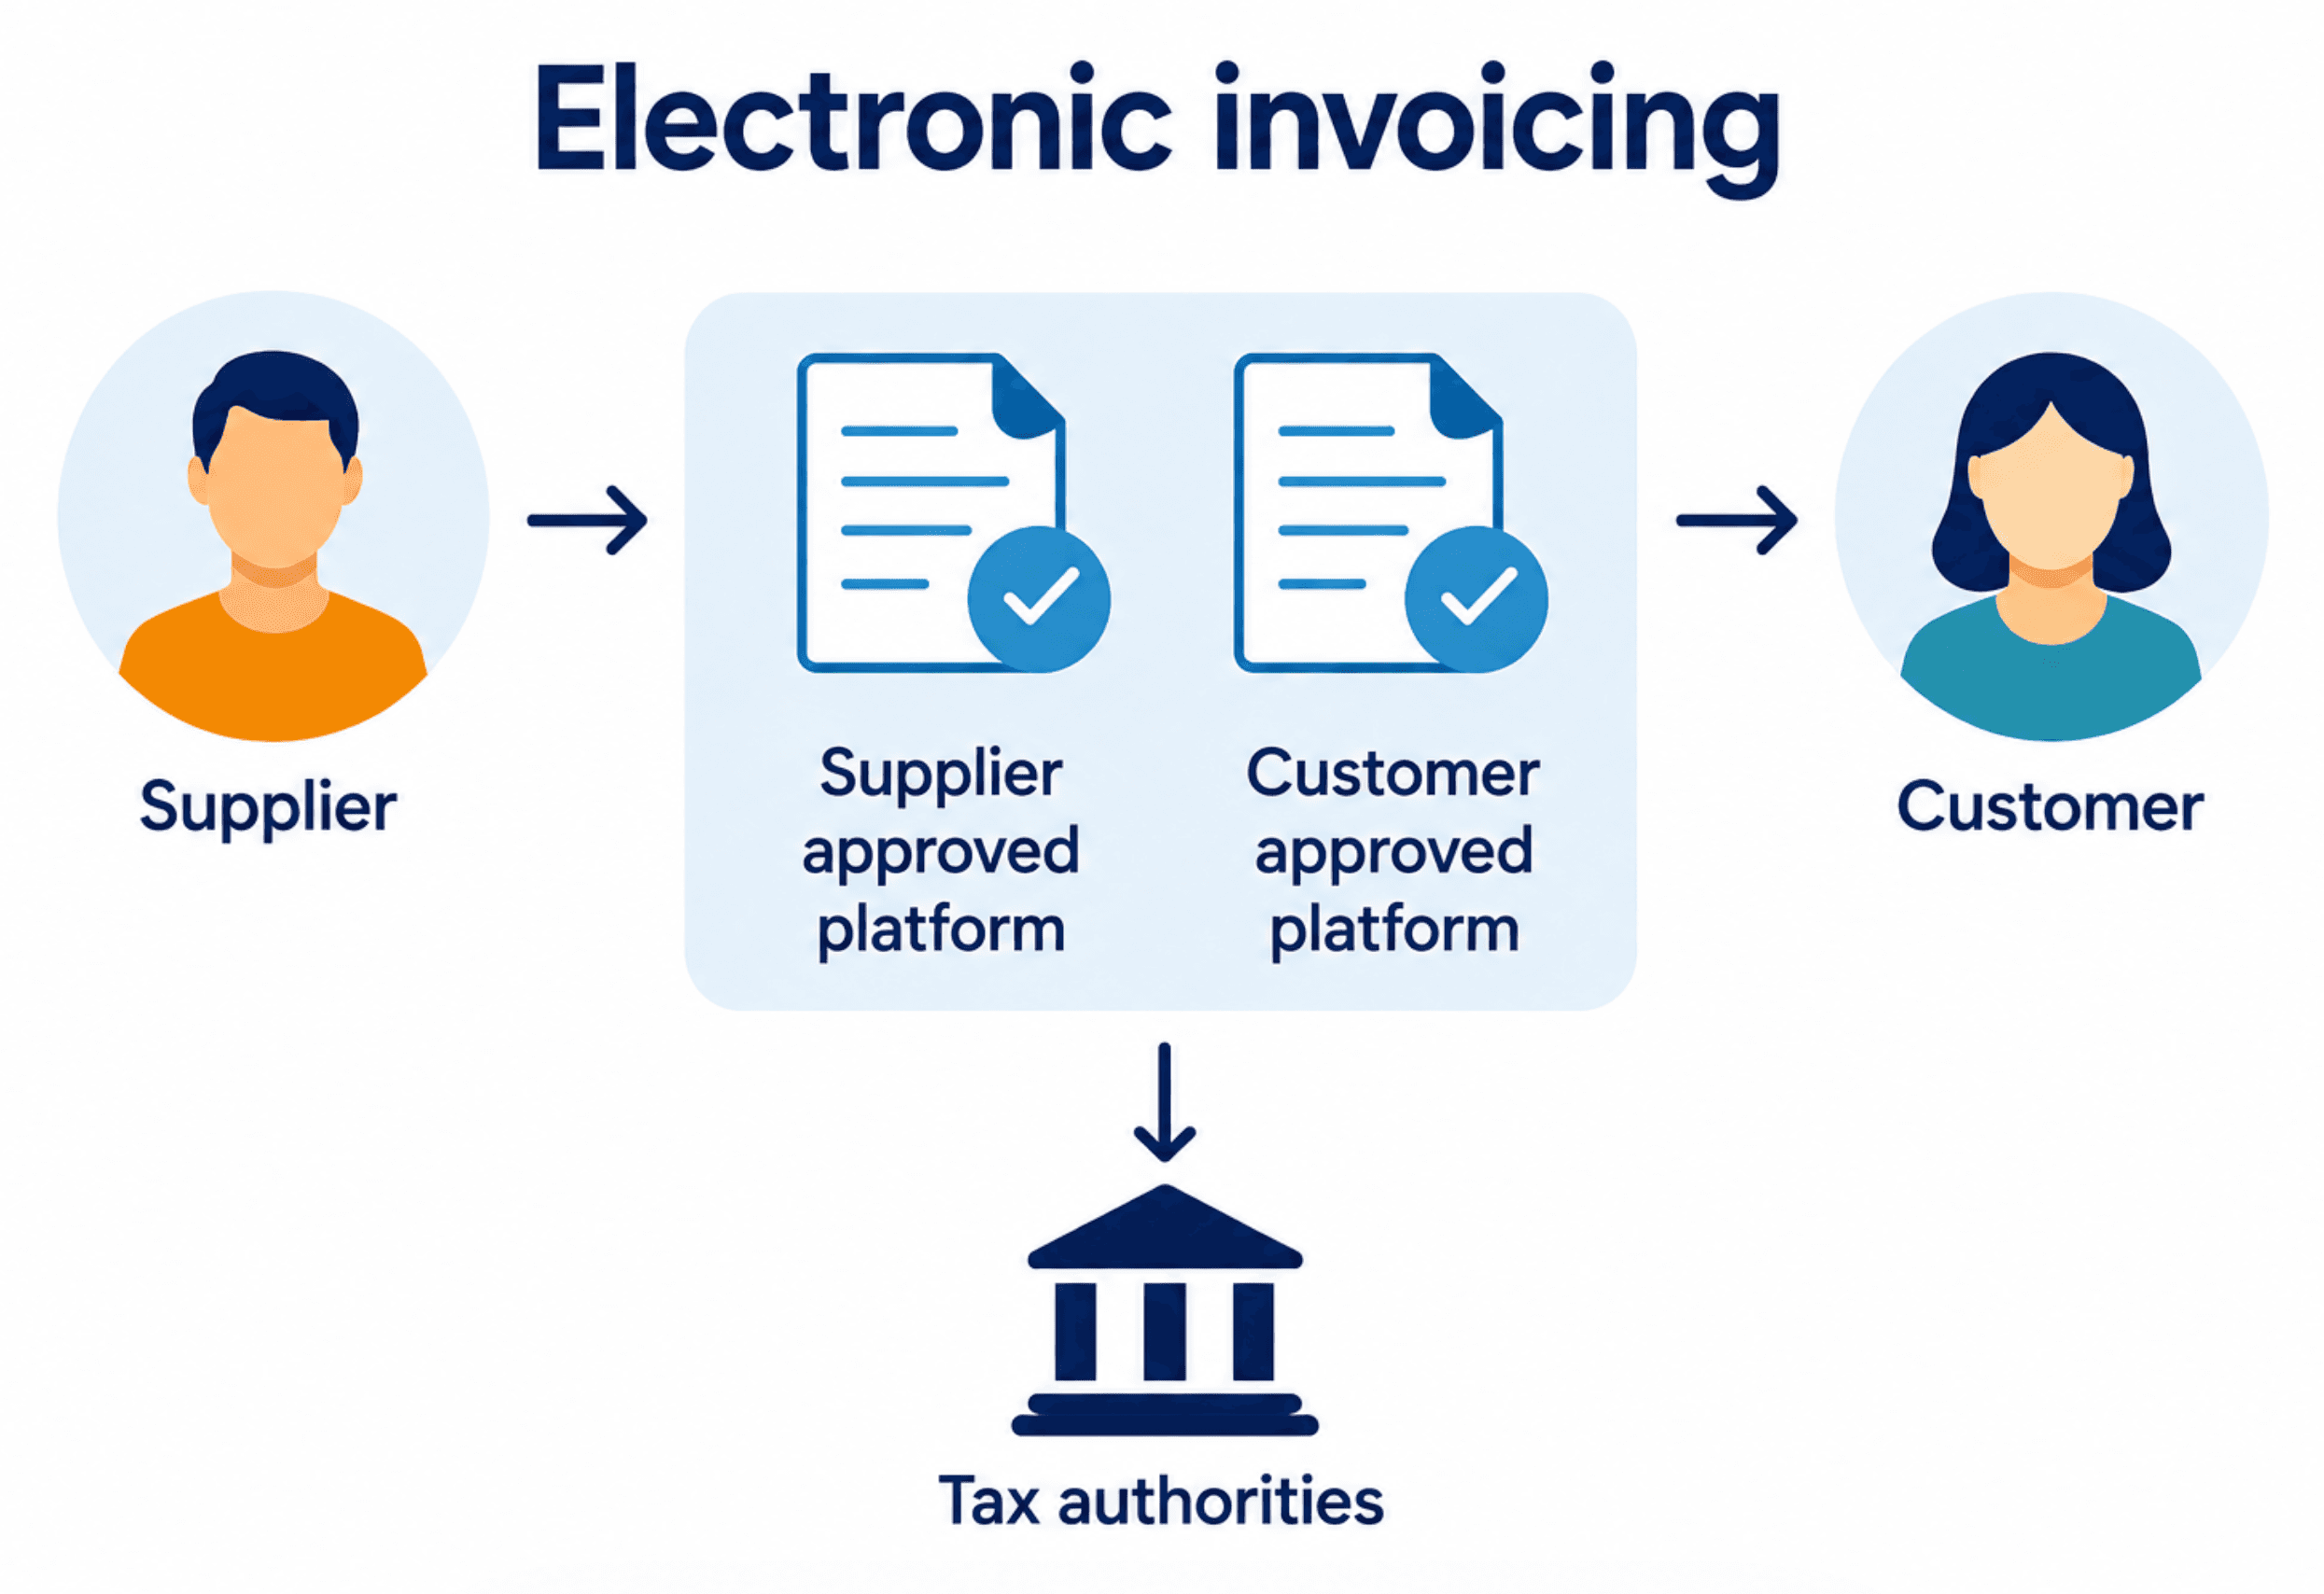
It applies to sales of goods and services between companies established in France. Your invoice leaves your software, goes through your approved platform, lands on your client's platform.
You follow its status in real time. Sent, received, accepted, rejected. Proof of delivery stops being a matter of opinion with a client who drags their feet on payment.
E-reporting covers the data from your other sales
No electronic invoice is required here. You simply pass the transaction details to the tax authority.
Three cases fall inside this scope:
- Your sales to private individuals.
- Your sales to clients based abroad, whether businesses or individuals.
- The payment data for your service work.
Your client still gets a PDF or a piece of paper. Under the French VAT exemption scheme for small turnovers, the data goes out every two months, and your software handles it without you lifting a finger.
Billing individuals only does not put you outside the reform. You escape issuing electronic invoices, but e-reporting still applies to you, and so does the duty to receive your suppliers' invoices.
The two dates that decide your calendar
The rollout happens in two waves, based on company size. The first step applies to you whatever your size.
| Date | Obligation | Who is targeted |
|---|---|---|
| September 1, 2026 | Be able to receive electronic invoices through an approved platform | Every business subject to VAT |
| September 1, 2026 | Issue electronic invoices and do e-reporting | Large companies and mid-sized companies |
| September 1, 2027 | Issue electronic invoices and do e-reporting | Small businesses and sole traders |
Hold on to that first row. In September 2026 a one-person business changes nothing about its own invoices, but has to be reachable by its French suppliers through a platform.
Your hosting provider, your phone operator and your emailing tool will switch before you do. With no platform registered, their invoices have nowhere to land.
The schedule has already moved once. The reform went into the amended finance law of 2022, with a start date planned for 2024, then got pushed back. The French state also announced a free public portal open to everyone, before dropping it in favour of privately run registered platforms only.
Who is affected, depending on who you bill
The rule fits in one sentence. Every business subject to VAT and established in France falls inside the scope, including those under the VAT exemption scheme.
Being exempt means you charge no VAT to your clients, because your turnover stays under the threshold. In the eyes of the law you are still subject to VAT.
What you owe exactly then depends on your client base.
| Your clients | Issuing | Receiving | E-reporting |
|---|---|---|---|
| Private individuals only | Not concerned | Sept. 1, 2026 | Sept. 1, 2027 |
| French businesses only | Sept. 1, 2027 | Sept. 1, 2026 | Not concerned |
| Individuals and French businesses | Sept. 1, 2027 | Sept. 1, 2026 | Sept. 1, 2027 |
| Clients based abroad | Not concerned | Sept. 1, 2026 | Sept. 1, 2027 |
The rare exceptions cover VAT-exempt operations that come with no invoicing duty: healthcare, education, banking, insurance. Even in those cases, your suppliers will keep sending you their invoices in electronic format.
Picking an approved platform without losing a weekend
An approved platform is a private provider registered by the DGFiP, the body that runs French public finances. It issues, transmits and receives your invoices, converts formats when needed, and forwards the data to the tax authority.
Registration is granted for three years and can be renewed, through a dedicated service. More than a hundred platforms appear on the list published by impots.gouv.fr, and it keeps growing.
Watch the sales vocabulary. A so-called "compatible" solution can build an invoice in the right format, but it has no right to transmit it to your client's platform or receive on your behalf. An approved platform has to sit at the end of the chain.
Your starting point is the tool you already use. Invoicing software aimed at French freelancers, such as Indy or Abby, is either registered or partnered with a platform, and handles the conversion in the background.
If you produce your invoices in Word, Excel or Canva, that road ends on September 1, 2027 for your business clients. You will have to move to compatible software or sign up directly with a platform.
On price, several platforms offer a free tier that easily covers a handful of invoices a month. The others charge a fixed subscription plus a variable share based on the number of documents processed. Compare against your real volume before you sign.
One note for anyone invoicing from their own application. If you sell a micro-SaaS on recurring billing, check that the platform exposes a documented API so you can push your invoices into it automatically.
What this changes for you, even working alone
You stop chasing proof that an invoice actually arrived. The status comes back into your tool: transmitted, received, accepted, rejected. A dunning email then rests on a timestamped delivery date, not on your memory.
You start treating your identification details as a working asset. An official directory ties your company number to the platform that receives on your behalf. Get the routing address wrong, and your suppliers' invoices vanish into nothing.
You pick your invoicing tool on compliance before features. "My quotes look good in this template" drops below "my tool is wired to an approved platform". For a solopreneur, switching tools costs half a day: better to spend it ahead of the deadline than on the day a client asks for their invoice.
What doing nothing costs you
Two consequences exist, and the most immediate one is not financial. With no platform registered by the receiving deadline, some supplier invoices never reach you, so you lose track of deductible expenses.
The French tax code also sets out fines, applied after a formal notice that goes unanswered. They target the absence of a platform, each invoice not transmitted in electronic format, and each missing data transmission, with an annual cap.
Those amounts have already been revised since the text was first voted. Check them on the official page rather than in an article, this one included.
The reform grows out of a European move started by Directive 2014/55/EU, and Italy made electronic invoicing general as early as 2019. The stated goal of the French state is fighting VAT fraud, with pre-filled tax returns promised in return.
Frequently asked questions
I am under the VAT exemption scheme, does this really apply to me?
Yes. The reform targets every business subject to VAT established in France, including those under the exemption scheme. Not charging VAT does not take you out of scope.
You must be able to receive electronic invoices from September 1, 2026, then issue them to your business clients from September 1, 2027.
Is a PDF sent by email enough to comply?
No. An electronic invoice under the reform carries structured XML data and travels through an approved platform. A PDF sent from your inbox meets neither condition for an invoice between businesses.
Do I have to change invoicing software?
Not always. If your software is already registered or connected to an approved platform, you carry on working exactly as before.
If you build your invoices in Word, Excel or Canva, you will need to move to compatible software or sign up directly with an approved platform.
I only bill private individuals, what do I have to do?
You keep sending them ordinary invoices, as a PDF or on paper. E-reporting does apply to you from September 1, 2027, meaning you pass your sales data to the tax authority.
You also have to be able to receive your suppliers' electronic invoices by September 1, 2026, like every business subject to VAT.
How much does an approved platform cost?
It depends on your invoice volume. Several platforms offer a free tier suited to a few invoices a month, which covers the situation of many freelancers.
Paid plans usually combine a fixed subscription with a variable share tied to the number of documents. Compare the prices each platform publishes, starting from the official DGFiP list.